

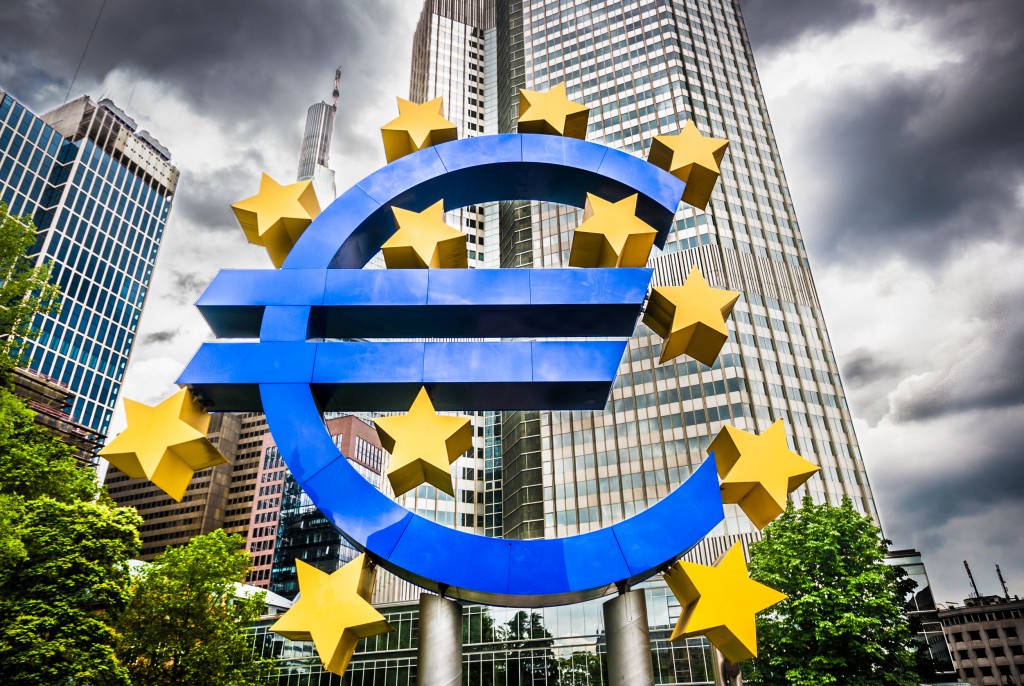
ECB to Begin Aggressive Tightening, Favoring Euro Bulls
The end of the month in the currency area is expected. Including yesterday’s US weekend, aggregate flows were low during the Asian and London hours but saw a buying trend for the euro following inflation data from Spain and Germany.
Talks in the trading community mainly focused on last week’s issues, namely the tightening of European Central Bank policy and the dollar weakening. We have some interesting sessions ahead of next week’s monetary policy decision, the ECB’s updated growth and inflation forecasts, and further guidance from European Central Bank President Christine Lagarde.

Late May flows were expected to support the dollar, and we saw some support last week. One interbank trader told me they don’t expect much flow on that front today, especially since US stocks have been rallying lately. This, in turn, tells me that the euro has room to grow further.
It’s about the asymmetry of the ECB. For cash traders, the probability of a 50 basis point hike in July is almost the same as a 25 basis point hike. Chief Economist Philip Lane said yesterday that monetary policy normalization would be gradual and that “the underlying pace is a 25 basis point rise for the July and September meetings”. That’s a clear statement, but it leaves room for further amelioration, as with Lagarde’s recent comments. And since Lane belongs to the moderate camp of the Governing Council, this can generally be taken as a hawkish statement.
Whether a historic 50 basis point move is likely to materialize is something that forex traders will see in the options market. The euro volatility divergence remains in favor of the dollar but at much less bearish levels for the single currency than in mid-May. If we see further repricing and an initial move at a premium to bullish euro rates, it could be taken as a strong sign that traders are expecting a dovish ECB outlook and a high risk of a half a percentage point hike by September.

The interest rate differential between the US and Germany continues to narrow, while medium-term inflation expectations have marked a short-term bottom for the eurozone. Analysis of euro-dollar spreads and EU-US swaps 1-2 years from now shows that a move towards $1.13 could be in the pipeline. With a few big “buts”: how the situation with Covid is developing in China and whether the military conflict in Ukraine will become a major obstacle again. So far, the surge above the 55-day moving average speaks for the first time since February on news that EU leaders have agreed to a partial ban on Russian oil, paving the way for the sixth round of sanctions to punish Moscow, speaks for itself. There is already momentum for further downside in the dollar, but as we said last week, beware of false breakouts amid month-end cash flows and liquidity cuts due to the holiday season. Starting tomorrow, we can even talk about seasonality.
CFDs are complex instruments and carry a high risk of rapid losses due to margin trading. Consider whether you understand how CFDs work and whether you can afford the risk of losing your money. This article is for educational purposes and is not investment advice.
Author: Andrew Trent
Andrew holds a degree in Data and Statistical Analysis and brings a tech nerd's curiosity to his writing. Off the clock, he's modeling data scenarios for fun, scuba diving, or taking underwater photos. He lives with his two Labradors, Homer and Duff, and his cat, Fibonacci.
Reviewed by: Chris Blakely
Content Editor with over two decades in financial journalism and a degree in Computer Engineering from the Polytechnic of the South Bank. Chris checks every article for factual accuracy and verifies claims before publication.
Last updated: May 31, 2022
Related Reading
Trader Sentiment
Share your outlook and see the results.
Bullish or bearish on EURUSD today?
Bullish or bearish on Bitcoin today?
Trending topics
FOREX HEATMAP
