

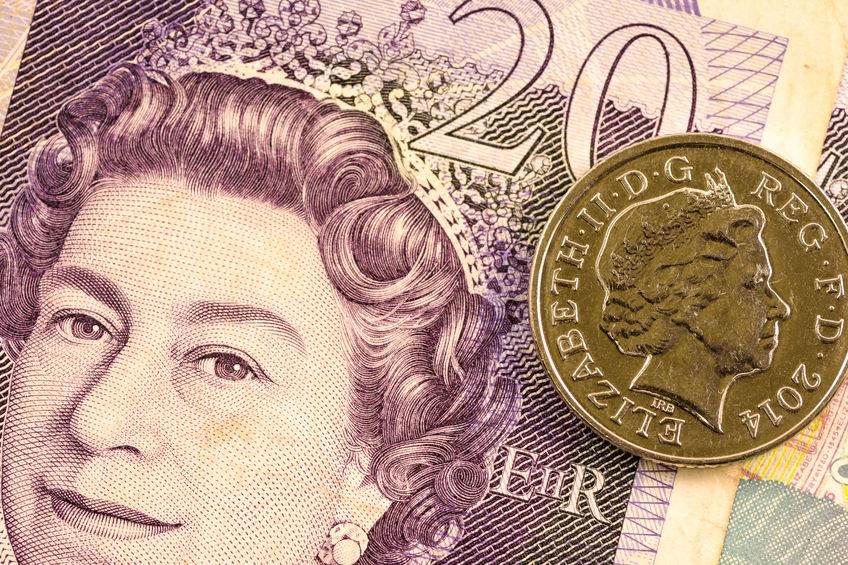
Disappointing employment news from Australia yesterday, along with the UK Retail Sales; today a light session ahead
Yesterday we have witnessed some disappointing news from Australia, where the employment rose less than forecasted, causing the currency to dip. The employment was weaker than the consensus and Nomura estimates, with seasonally adjusted 4,900 persons in March, as opposed to the 20,300 forecasted. The unemployment rate was the same as the estimate, coming at 5.5%. In 2017 an epic number of 400k jobs were added and the RBA has predicted that hiring would be above the average pace in the coming months of 2018. However, there was an impact on those gains on the jobless rate mainly by high immigration. According to Governor, Philip Lowe, there is not a strong case in the near future to raise the interest rates from 1.5%, as opposed to his global counterparts. Furthermore, the prospect of the US-China trade war has seen the Australian dollar being the strongest of the G10 currencies over the past week.
Investors were looking closely at the retail sales numbers yesterday, which unfortunately did not manage to sustain the expectations. Namely, an up rise would have offered a fresh push to the bullish sentiments, however the numbers have shown retail sales had a bigger than expected drop in March. The expectations were that the retail sale would come at negative 0.5% and turned out to be -1.2%. The miss of the forecasted numbers are assumed to be influenced by the cold weather in March, thus forcing the British shoppers to remain in their homes. After the data was released, sterling has dropped to one week low. Taking into consideration this week’s wage rise being slower than expected and the inflation dropping quicker than expected, doubts have been raised about the BoE interest rate rise. It is yet to be seen if the Bank of England would be increasing the rates next month.
Today we do not have a lot of macroeconomic news releases, with the only high impact news coming from Canada, where we are waiting for the CPI and Core retail sales results for the previous month. The EU calendar is quiet today, with BoE MPC member Saunders to speak, as well as ECB Governing Council member Weidmann’s speech. In addition, IMF 3 day meeting will start today, where the main focus will be on the trade issue and global growth forecasts. From the US, the FOMC member Williams will remain in focus.
ECONOMIC CALENDAR EVENTS FOR APRIL 20th
EUR German PPI m/m
EUR Consumer Confience
GBP MPC Member Saunders Speaks
EUR German BUB President Weidmann Speaks
CAD CPI m/m
CAD Core Retail Sales m/m
USD FOMC Member Williams Speaks
CFDs are complex instruments and carry a high risk of rapid losses due to margin trading. Consider whether you understand how CFDs work and whether you can afford the risk of losing your money. This article is for educational purposes and is not investment advice.
Author: Andrew Trent
Andrew holds a degree in Data and Statistical Analysis and brings a tech nerd's curiosity to his writing. Off the clock, he's modeling data scenarios for fun, scuba diving, or taking underwater photos. He lives with his two Labradors, Homer and Duff, and his cat, Fibonacci.
Reviewed by: Chris Blakely
Content Editor with over two decades in financial journalism and a degree in Computer Engineering from the Polytechnic of the South Bank. Chris checks every article for factual accuracy and verifies claims before publication.
Last updated: April 20, 2018
Related Reading
Trader Sentiment
Share your outlook and see the results.
Bullish or bearish on EURUSD today?
Bullish or bearish on Bitcoin today?
Trending topics
FOREX HEATMAP
